The Canada Pension Plan might seem like a simple retirement benefit, but the math behind it tells a different story. Most people don’t realize that taking CPP early means accepting a permanent reduction in monthly payments, while waiting until later can boost your benefits significantly. This creates a financial puzzle that many Canadians struggle to solve.
When you start collecting CPP can significantly change your lifetime retirement income. Starting early means locking in a lower monthly amount, while waiting boosts your payments for life. The structure favors those who can afford to delay, creating tough trade-offs for workers with limited options.
The Real Cost of Taking CPP Early
Claiming CPP at age 60 may feel like getting ahead, but it comes with a lifelong reduction in benefits. Your monthly payment drops by 0.6% for each month before 65, up to a total cut of 36%. This reduction applies to the amount you would have received at 65, based on your contribution history. For example, if you’re entitled to $1,000 at 65, starting at 60 drops it to just $640 per month—for life.
The 42% Bonus for Waiting Until 70
Delaying your CPP benefits beyond age 65 leads to a permanent monthly increase of 0.7% for each month you wait. If you hold off until age 70, that adds up to a 42% boost over your age-65 amount. A $1,000 monthly benefit at 65 could grow to $1,420 by 70, for life. This higher amount becomes your new baseline and doesn’t decrease once payments begin.
Understanding Maximum CPP Benefits
The maximum CPP payment at 65 is $1,433.00 per month, but only if you contributed the maximum each year. Many Canadians get less—an average of $844.53—due to lower or uneven contributions. These amounts are based on your lifetime earnings and adjusted yearly for inflation. Since CPP replaces just 25 to 33% of your income, it often isn’t enough by itself.
Break-Even Analysis: When Waiting Pays Off

Delaying CPP only makes sense if you expect to live long enough to recover the lost early payments. The break-even point for starting at 60 versus 65 is just before age 74, based on standard benefit rates. If you live past 80, deferring until 70 gives you more total income over time. However, this strategy assumes you can rely on other savings or income while you wait.
Why Most Canadians Can’t Actually Wait

Many Canadians can’t afford to delay CPP until 70, even if the math shows higher lifetime benefits. Job loss, poor health, or limited savings often push people to claim early. As of April 2025, new beneficiaries received an average of just $844.53 per month. Even those who understand the trade-offs may need the money right away to cover basic expenses.
The Hidden Costs of Working Until 70
Working until 70 to boost CPP benefits often comes with real-world trade-offs that numbers don’t show. After age 60, ageism can make finding or keeping a job much harder, especially after layoffs. Health declines and caregiving duties can also interfere with your ability to work or enjoy life. For many, the emotional and physical toll of staying employed outweighs the promised financial gains.
Health Considerations and Life Expectancy

Health is a major factor when deciding the best time to start CPP benefits. Those with serious health issues or a shorter family lifespan may lose out by waiting too long. While Canada’s average life expectancy is about 82, many people fall short of that due to illness or hardship. Relying only on break-even math ignores the risk of not living long enough to benefit.
Impact on Spousal Benefits and Survivor Pensions

When you start CPP affects not just you, but also your spouse’s future income. If you pass away first, your spouse may receive a survivor pension based on your CPP amount. Taking CPP early lowers both your payments and what your spouse could later receive. Delaying until 70 helps maximize survivor benefits and long-term financial security.
Tax Implications of Different CPP Timing Strategies
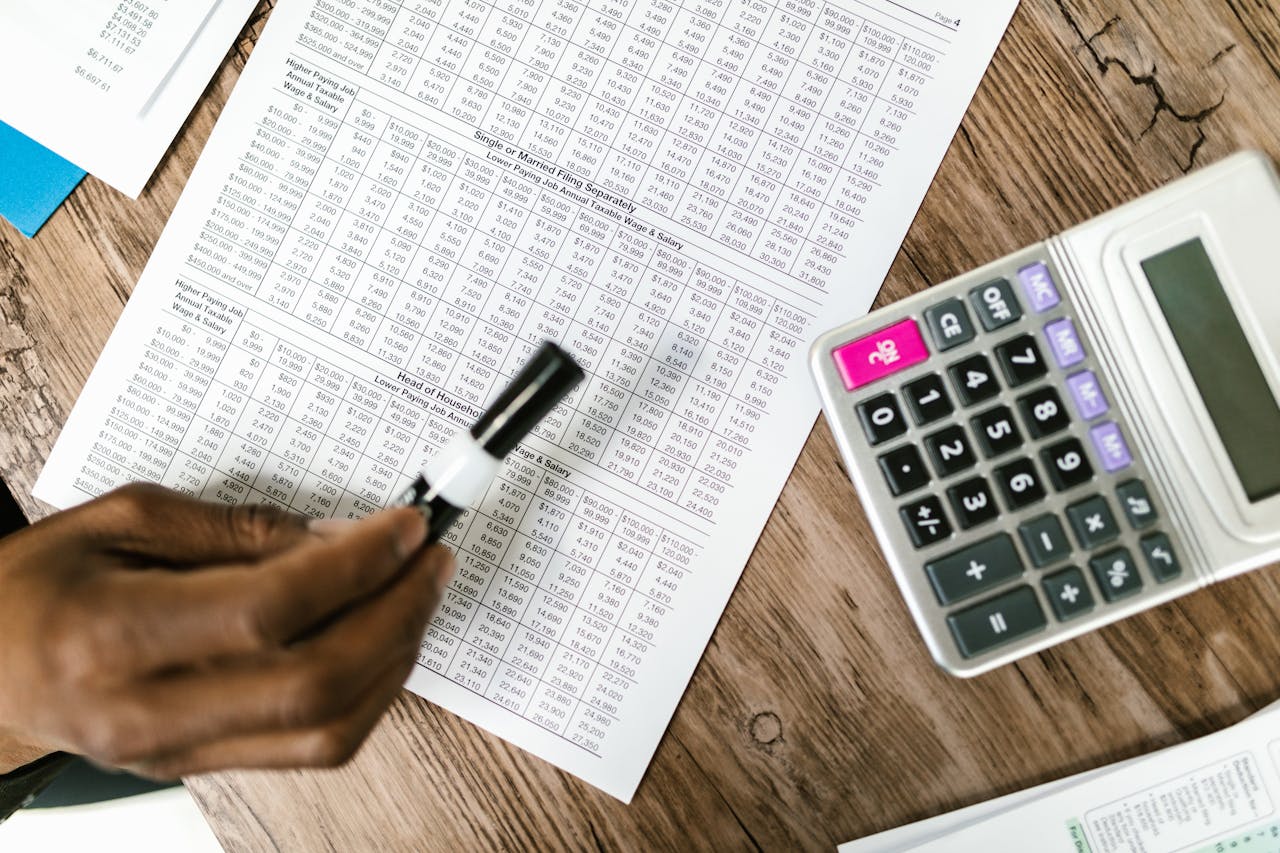
CPP payments count as taxable income, so when you take them can impact how much tax you owe. Starting early while still working may increase your income and push you into a higher bracket. Delaying until 70 could mean higher CPP payments, but taxed at a lower rate if other income has dropped. Coordinating CPP with OAS and other sources adds complexity that calls for smart tax planning.
Alternative Income Sources While Waiting
Delaying CPP until 70 means you’ll need other income to cover retirement years in the meantime. This can come from workplace pensions, RRSPs, TFSAs, or part-time work. Many Canadians—especially those with lower earnings or gaps in employment—don’t have enough savings to wait. The strategy mainly benefits higher earners who can afford to delay without sacrificing essentials.
The Role of Old Age Security in Your Decision
OAS begins at age 65 regardless of when you claim CPP. From July to September 2025, the maximum monthly OAS is $734.95 for ages 65–74 and $808.45 for those 75 and older. Benefits are reduced if your 2024 income exceeds $90,997, and fully clawed back at $148,541. Delaying CPP to age 70 can boost your income but may also reduce your OAS through the recovery tax, so careful planning is essential.
Making the Decision: Factors to Consider
Choosing when to take CPP depends on your full financial and personal situation—not just the numbers. Think about your debt, housing costs, family needs, and the kind of retirement you want. Some prefer early income at 60 for peace of mind, while others wait to boost long-term payments. It’s a personal choice shaped by both financial realities and emotional comfort.
Ways to Maximize Your CPP Payments in Retirement